When Your Car Is Totaled: How Total Loss Claims Work
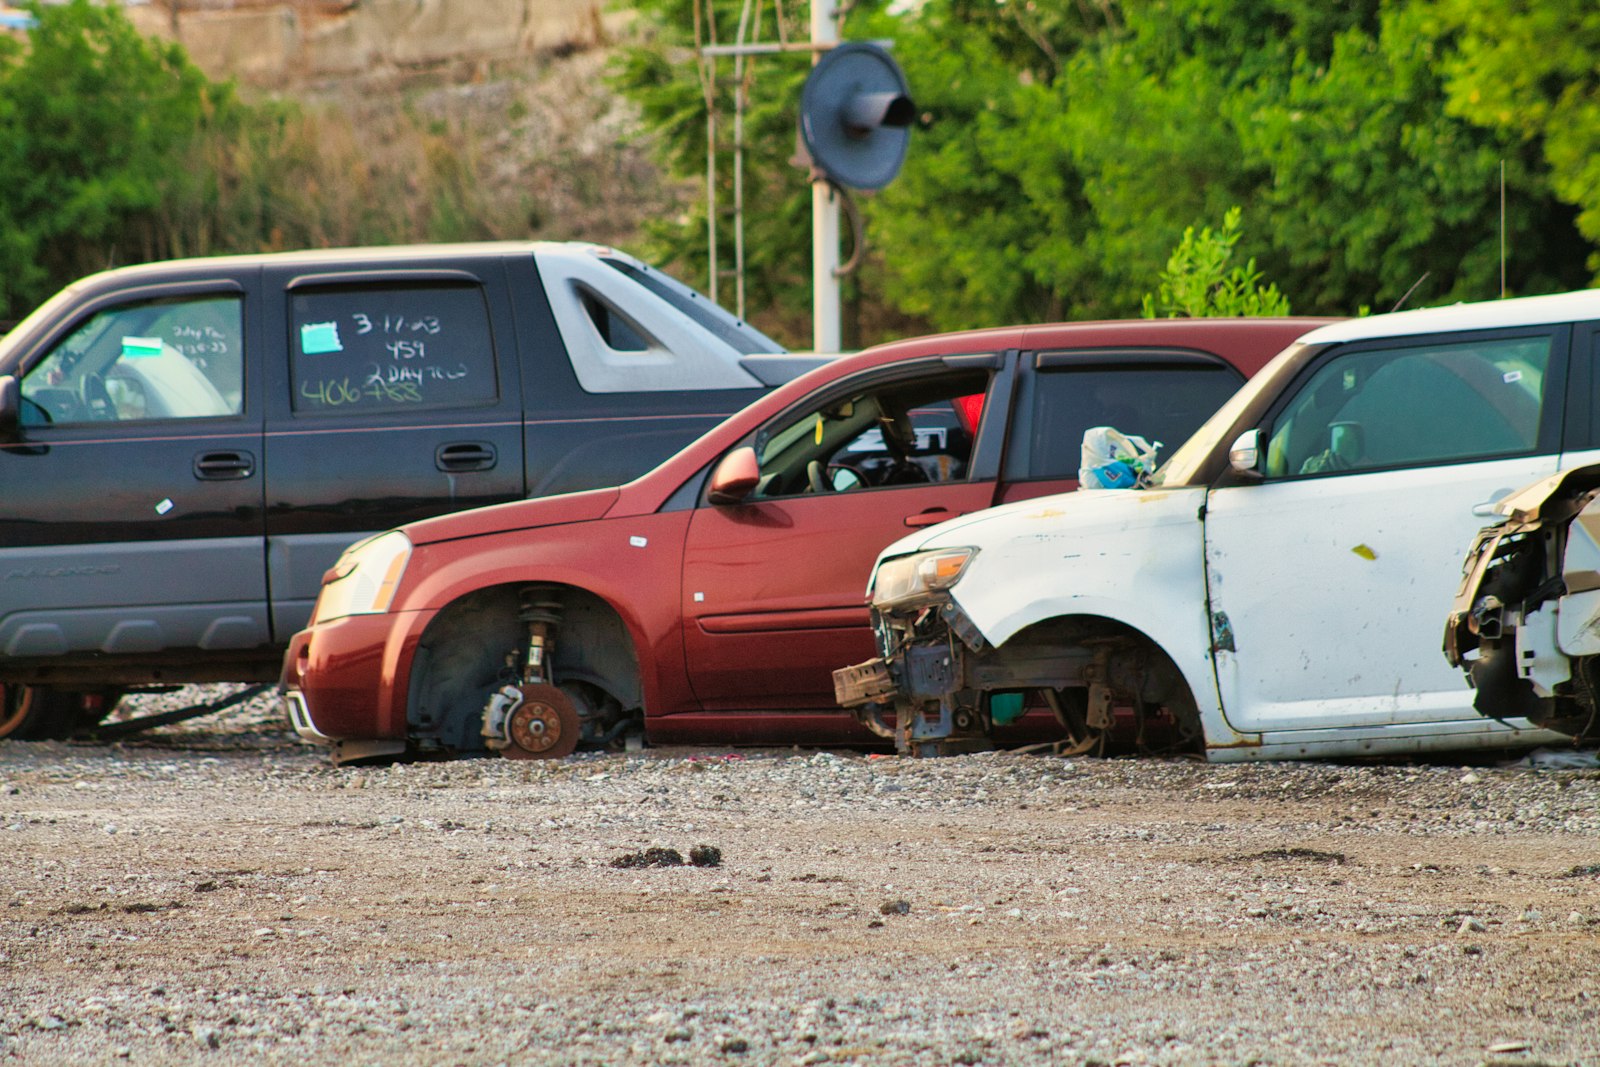
A total loss means the insurer pays you the car’s value instead of repairing it. Understanding how that value is set helps you get a fair settlement.
Quick checklist
- A car is usually totaled when repairs would cost too much compared with its value, under a formula or threshold set by your state.
- The payout is based on the car’s actual cash value just before the accident, minus your deductible.
- If you owe more on a loan than the car is worth, gap insurance can cover the difference.
- You can challenge a low valuation with evidence of comparable vehicles for sale.
- Some insurers let you keep the car, but it will usually need a salvage title.
If your car is badly damaged, your insurer may declare it a total loss. Instead of paying for repairs, it pays you what the car was worth.
When a car is totaled
Insurers compare the cost of repairs, sometimes plus the salvage value, with the car’s value. States set the rules:
- Threshold states declare a total loss when repair costs reach a set percentage of the car’s value.
- Formula states use a calculation comparing repair costs and salvage value with the car’s value.
Older cars are totaled more easily, because modest repairs can exceed their value.
How the payout is calculated
The settlement is based on actual cash value (ACV): what your car was worth just before the accident, considering its age, mileage, condition, options and local market prices. Your deductible is subtracted.
Driver tip
Before accepting an offer, gather listings for similar cars for sale near you: same year, model, trim and mileage. Records of recent major repairs or new tires can also support a higher value.
If you owe more than the car is worth
If your loan balance is higher than the ACV, you still owe the difference. Gap insurance, if you bought it, covers that gap. Without it, you’ll need to pay off the remaining balance.
Disputing a low offer
- Ask for the valuation report and check it for mistakes, such as the wrong trim or missing features.
- Submit your own evidence of comparable vehicles.
- Use the appraisal clause in your policy, if it has one, which lets each side hire an appraiser.
- Contact your state insurance department if you believe the insurer isn’t acting fairly.
Next steps
Remove personal items from the car and arrange for the title to be transferred. Our guide to filing a claim covers the wider process, and if you need a car in the meantime, see our guide to rental car insurance.
Driver questions
Who decides if my car is totaled?
Your insurer, based on repair estimates and the car’s value, following your state’s rules. Some states set a percentage threshold; others use a formula.
Can I keep my totaled car?
Often, yes. The insurer deducts the salvage value from your payout, and the car may need a salvage title and inspection before it can be driven again.
Do I keep paying my car loan?
Yes, until the loan is paid off. The insurer usually pays the lender first, and you receive anything left over.
Does the payout include sales tax and fees?
In many states, total loss settlements include sales tax and some fees for a replacement vehicle. Ask your adjuster how your state handles it.
Car insurance rules vary by state and by policy. This guide is general information, not legal or insurance advice; check your policy and your state insurance department for details.